Earnings analysis
Ducommun's military and space bookings outpace sales
Commercial aerospace drives quarterly revenue growth, while military and space dominate net bookings. Customer advances support cash generation as Ducommun reduces debt.
In this analysis
Ducommun · Q3 2026 · Quarter ended October 3, 2026 · Results issued November 5, 2026.1
Ducommun's third-quarter sales grew on commercial aircraft work, while military and space supplied most of its net bookings.1,2 Revenue reached $227.0 million, up 5.9% from the restated prior-year quarter.1 Sales rose 1.1% from the second quarter.1,3
Military and space remaining performance obligations rose in the third quarter while commercial aerospace RPO declined, but the earnings improvement is uneven.1,3 Electronic Systems expanded operating profit while Structural Systems earned less on higher revenue.1 Customer advances contributed to operating cash as Ducommun reduced borrowings.2
This assessment covers the earnings releases, filings and presentation. It does not assess the earnings call or analyst Q&A.
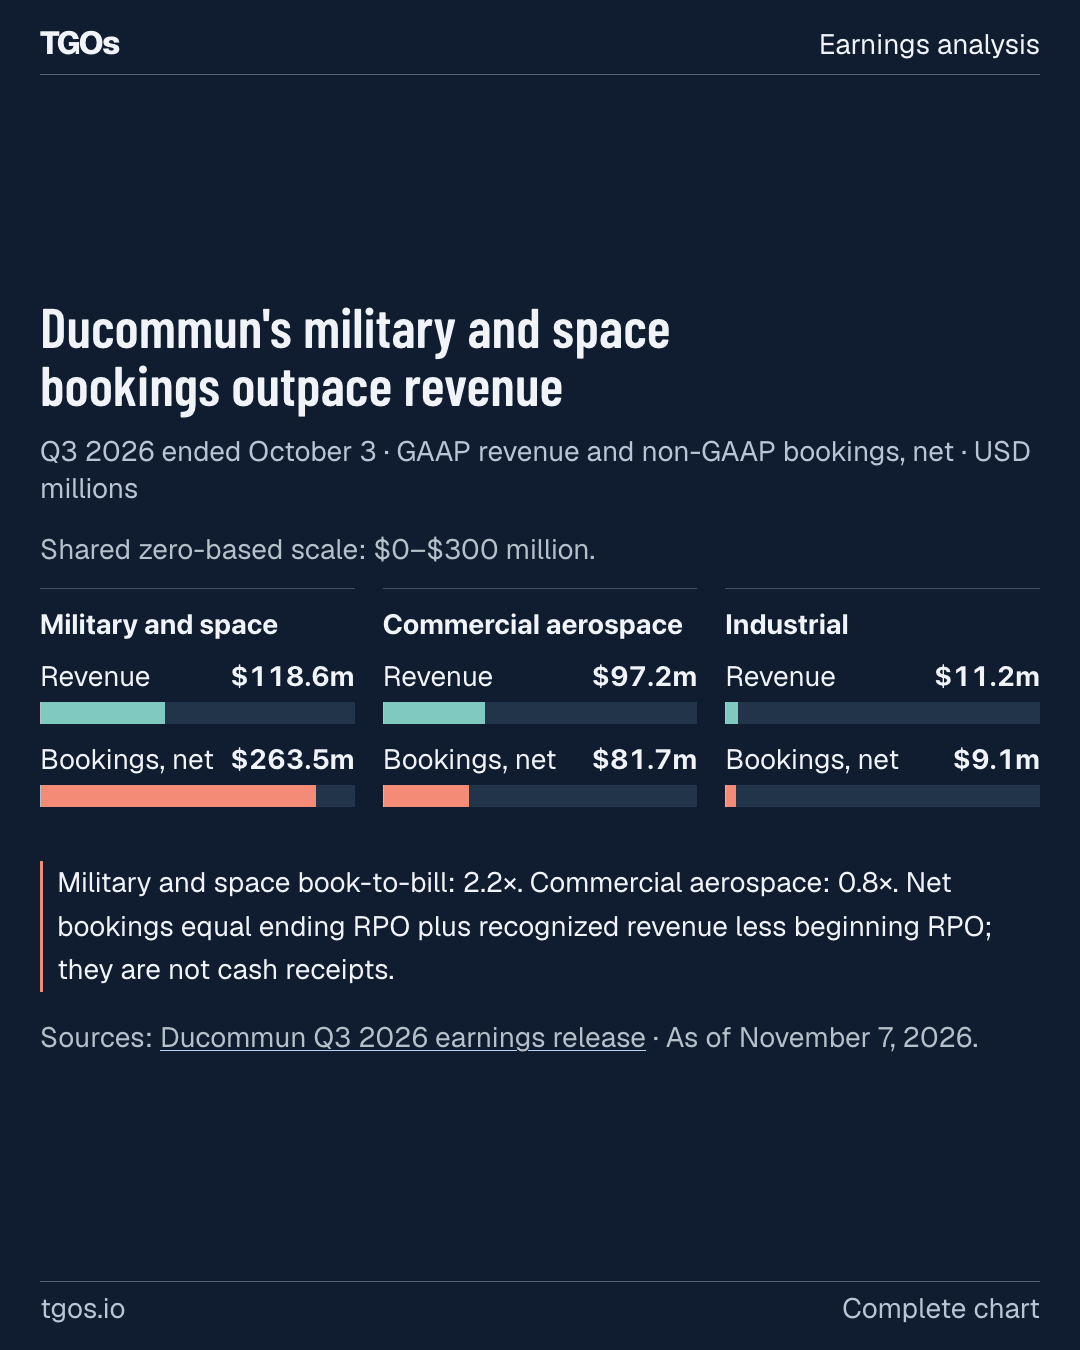
Ducommun's military and space bookings outpace revenue
Q3 2026 ended October 3 · GAAP revenue and non-GAAP bookings, net · USD millions
Ducommun's military and space bookings outpace revenue. Q3 2026 ended October 3 · GAAP revenue and non-GAAP bookings, net · USD millions. Military and space: Revenue $118.6m, Bookings, net $263.5m. Commercial aerospace: Revenue $97.2m, Bookings, net $81.7m. Industrial: Revenue $11.2m, Bookings, net $9.1m.
Shared zero-based scale: $0–$300 million.
Military and space
Commercial aerospace
Industrial
Military and space book-to-bill: 2.2×. Commercial aerospace: 0.8×. Net bookings equal ending RPO plus recognized revenue less beginning RPO; they are not cash receipts.1
Sources: Ducommun Q3 2026 earnings release · As of November 7, 2026.
Commercial aircraft carry the revenue increase
Commercial aerospace revenue rose 27.7%, more than offsetting the 7.2% decline in military and space. The commercial increase reached both operating segments; almost all of the military and space decline fell in Electronic Systems.2
Chairman, President and Chief Executive Officer Stephen G. Oswald attributed commercial growth to the Boeing 737 MAX and Airbus A320 single-aisle platforms in Ducommun's November earnings release.1 The earnings presentation says Boeing destocking is unwinding through the fourth quarter.4 That is consistent with the gradual easing Oswald described in August, when he still expected destocking headwinds through the remaining quarters of the year.3
Oswald attributed the defense weakness to order and production timing on ground vehicles, Blackhawk and Apache helicopters, and selected radar programs. He reported growth on Tomahawk, MIR and TOW missiles and the F-15.1 The filing also attributes the decline to lower rates on selected platforms, partially offset by missiles and fixed-wing aircraft.2
The decline in military and space revenue coincided with RTX's share of quarterly revenue rising to 23.1% from 19.3%. The filing says revenue from RTX, Boeing and Northrop Grumman spans multiple programs and both segments. We therefore cannot use customer shares alone to identify the program behind a change.2
Ducommun's order book shifts toward defense
Total net bookings grew 4.3% year over year, leaving the reported companywide book-to-bill ratio unchanged at 1.6. Beneath that total, military and space bookings rose 34.9%, while commercial bookings fell 39.5%.1
The sequence within 2026 also matters. Net bookings rose from $176.7 million in the first quarter to $309.7 million in the second.3 They reached $354.3 million in the third quarter.1 The first-quarter figure is our calculation from Ducommun's six-month and second-quarter disclosures.3 Bookings fell short of revenue in the first quarter, then exceeded it in both subsequent quarters.1,5,3
Ducommun defines net bookings as ending remaining performance obligations, plus recognized revenue, less beginning remaining performance obligations.1 Its presentation describes the measure as orders net of cancellations.4 We use the release's definition throughout. Remaining performance obligations, or RPO, are the unrecognized revenue on customer purchase orders with firm fixed prices and firm delivery dates.1
Ducommun's remaining performance obligations tilt toward military and space
Unrecognized revenue on qualifying purchase orders · USD millions · Same RPO basis throughout
Ducommun's remaining performance obligations tilt toward military and space. Unrecognized revenue on qualifying purchase orders · USD millions · Same RPO basis throughout. Dec. 31, 2025: Military and space $692.7m, Commercial aerospace $402.2m, Industrial $11.1m; total $1,106.0m. Apr. 4, 2026: Military and space $678.8m, Commercial aerospace $381.9m, Industrial $13.0m; total $1,073.7m. Jul. 4, 2026: Military and space $722.7m, Commercial aerospace $419.9m, Industrial $16.2m; total $1,158.9m. Oct. 3, 2026: Military and space $867.6m, Commercial aerospace $404.5m, Industrial $14.1m; total $1,286.2m.
Shared zero-based scale: $0–$1,400 million.
Dec. 31, 2025
$1,106.0m total- Military and space $692.7m
- Commercial aerospace $402.2m
- Industrial $11.1m
Apr. 4, 2026
$1,073.7m total- Military and space $678.8m
- Commercial aerospace $381.9m
- Industrial $13.0m
Jul. 4, 2026
$1,158.9m total- Military and space $722.7m
- Commercial aerospace $419.9m
- Industrial $16.2m
Oct. 3, 2026
$1,286.2m total- Military and space $867.6m
- Commercial aerospace $404.5m
- Industrial $14.1m
Military and space rises from 62.6% to 67.5% of remaining performance obligations between year-end and October 3. RPO is the unrecognized revenue on customer purchase orders with firm fixed prices and firm delivery dates.1 Orders remain subject to delays or cancellations.2
Sources: Ducommun Q3 2026 earnings release; Ducommun Q3 2026 Form 10-Q; Ducommun Q1 2026 earnings release; Ducommun Q2 2026 earnings release · As of November 7, 2026.
Electronic Systems accounted for 81.0% of the third-quarter increase in military and space RPO. Commercial RPO declined during the quarter, consistent with commercial revenue exceeding net bookings.1,3
Ducommun estimates that 70% of quarter-end RPO will become revenue over the following 12 months. The filing says RPO tends to be more concentrated in several programs than recognized revenue.2 The increase represents more unrecognized revenue on qualifying purchase orders, though orders can be delayed or cancelled and conversion timing is a company estimate.1,2
Electronic Systems converts growth into higher profit
Electronic Systems generated $28.7 million of operating income, up about 23% year over year. Segment revenue reached $129.6 million. Electronic Systems supplied 70.6% of combined segment operating income, before unallocated corporate expenses.1
The release attributes the segment's year-over-year profit increase primarily to higher manufacturing volume, partly offset by higher manufacturing costs.1 The presentation also credits operating leverage.4 Sequentially, the segment's margin rose even as revenue declined from the second quarter; management's year-over-year explanation does not isolate the cause of that quarterly change.1,4,3
Ducommun's segment operating margins move apart
GAAP segment operating income ÷ segment revenue · 2025 restated · Before unallocated corporate expenses
Ducommun's segment operating margins move apart. GAAP segment operating income ÷ segment revenue · 2025 restated · Before unallocated corporate expenses. Q3 2025 · prior-year comparison: Electronic Systems 18.6%, Structural Systems 13.7%. Q1 2026: Electronic Systems 19.5%, Structural Systems 11.4%. Q2 2026: Electronic Systems 19.4%, Structural Systems 13.7%. Q3 2026: Electronic Systems 22.2%, Structural Systems 12.3%.
Shared zero-based scale: 0–25%.
Q3 2025 · prior-year comparison
Q1 2026
Q2 2026
Q3 2026
Electronic Systems improves sequentially while Structural Systems retreats.1,3 The prior-year comparison is shown separately from the 2026 quarterly sequence; Q4 2025 is not shown.
Sources: Ducommun Q3 2026 earnings release; Ducommun Q1 2026 earnings release; Ducommun Q2 2026 earnings release · As of November 7, 2026.
Structural Systems' revenue rose to $97.4 million from $89.2 million. Operating profit fell 2.2%, and non-GAAP segment adjusted EBITDA declined 4.5%.1 In Structural Systems, the commercial aircraft ramp accompanied higher revenue without more segment profit this quarter.1,2
The release emphasizes unfavorable product mix as the reason for the profit decline.1 The filing adds higher manufacturing costs as a primary cause, with higher volume and facility-consolidation savings providing offsets.2
Higher overhead absorbs much of the gross-profit gain
At the company level, the gross-profit increase of $6.6 million met a $5.8 million increase in selling, general and administrative expenses.1 Ducommun attributes the higher expenses to compensation and benefits, professional services and other costs.2 Adjusted operating income grew 3.1%. Its non-GAAP margin slipped from 12.7% to 12.3%.1
Adjusted net income was effectively unchanged at $18.8 million. Adjusted diluted earnings per share fell to $1.21 from $1.22.1 Adjusted EBITDA rose 6.3%, although the margin gain over the prior year was much smaller than in the first two quarters.1,5,3
| Period | 2025 | 2026 |
|---|---|---|
| Q1 | 15.4%5 | 16.9%5 |
| Q2 | 15.8%3 | 17.1%3 |
| Q3 | 17.4%1 | 17.5%1 |
A larger stock-compensation add-back contributed to adjusted EBITDA growth. Subtracting that add-back in both years leaves growth of 2.6%. This is our analytical comparison, not a company-reported measure; it illustrates how the treatment of compensation affects the growth rate.1
The GAAP rebound was much larger: net income of $13.9 million followed a $60.8 million loss a year earlier. Ducommun attributes most of that swing to the absence of the prior year's litigation settlement and related costs.1 The charge concerned the Guaymas fire litigation settlement.2 The Q3 2025 charge preceded Ducommun's payment in the following quarter.1,2
The prior-year quarter also included a $23.0 million discrete tax benefit associated with the settlement costs.2 This quarter included a $3.9 million pension settlement loss.1 The $24.0 million payment to settle the pension obligations came from existing plan assets.2
The comparisons above use restated 2025 results.1 The restatement corrected stock-compensation timing and other items, including revenue and cost of sales recognized in the wrong periods. Ducommun reported ineffective disclosure controls at quarter-end because remediation of the stock-compensation material weakness had not yet been demonstrated effective.2
Customer advances support cash generation
Third-quarter operating cash was $32.7 million, compared with $18.1 million a year earlier.1 It was below the second quarter's $33.5 million.1,3 Nine-month operating cash rose to $77.5 million from $41.3 million. The nine-month periods end October 3, 2026, and September 27, 2025; they differ in length, unlike the equal-length third quarters.2
The increase in contract liabilities equaled 52.8% of nine-month operating cash. Ducommun attributes the liability increase primarily to customer advance or progress payments.2 Those receipts support current cash generation while leaving work to perform.1,2 Receivables and contract assets absorbed cash, with the filing attributing higher contract assets primarily to more work in process.2
Customer advances partly offset cash tied up in Ducommun's work
Selected working-capital cash-flow movements · Nine months ended October 3, 2026 · USD millions
Customer advances partly offset cash tied up in Ducommun's work. Selected working-capital cash-flow movements · Nine months ended October 3, 2026 · USD millions. Contract liabilities: +$40.9m. Accounts receivable: −$38.5m. Contract assets: −$25.9m.
Shared scale: −$50 million to +$50 million. Positive values add operating cash; negative values absorb it.
Ducommun attributes the contract-liability increase primarily to customer advance or progress payments. Selected movements are components of operating cash flow, not a complete cash bridge.2
Sources: Ducommun Q3 2026 Form 10-Q · As of November 7, 2026.
Operating cash less cash purchases of property and equipment reached $65.2 million, against $30.1 million a year earlier. This is our calculation using cash capital spending, not a company-reported free-cash-flow measure.2
Ducommun repaid $53.8 million of revolver and term-loan borrowings over nine months. Debt less cash, calculated from the filing's rounded balances, fell to $212.1 million from $259.7 million at year-end. The weighted-average debt rate also declined, to 5.53% from 6.10%.2
The filing separately records $17.4 million of net cash paid upon issuance of common stock under stock plans. Cash balances declined by $6.1 million over nine months despite the higher operating inflow.2
Ducommun plans capital expenditures of $20 million to $22 million for the year, principally to support new contract awards in both segments.2 Through nine months, the segment table records $11.9 million of capital expenditures, while cash purchases of property and equipment were $12.3 million. The two measures differ.1,2
Revenue guidance leaves a roughly level fourth quarter
Ducommun reiterated its $880 million to $890 million annual revenue outlook and expects to finish at the higher end, $885 million to $890 million. The presentation describes revenue growth for the year as mid to high single digit.4
| Period and basis | Revenue |
|---|---|
| 2025 actual, restated | $824.8 million6 |
| 2026 previously provided range, reiterated | $880 million–$890 million4 |
| 2026 expected higher end | $885 million–$890 million4 |
Subtracting nine-month revenue from the rounded higher-end expectation implies approximately $224.5 million to $229.5 million for the fourth quarter.2,4 That range is roughly level with the third quarter and above restated fourth-quarter 2025 revenue of $217.1 million.1,2,4,6 Fourth-quarter lengths can vary, limiting a like-for-like comparison of the revenue totals.2
The longer-term plan also depends on acquisitions.4 Ducommun's VISION 2032 annual revenue target is $1.6 billion to $1.7 billion.1 Alongside its organic growth target, the presentation includes a $250 million to $300 million placeholder for revenue added through acquisitions.4
At quarter-end, Ducommun had $394.8 million of unused revolving credit capacity.2 Its lower debt provides balance-sheet context for that ambition; the acquisition contribution remains a target.2,4 The nearer operating test is conversion: turning the larger defense order book into revenue while earning more from the commercial aircraft ramp.1,2